

The Indian economy is growing at a rapid rate and, as a result, the need for power is rising. As the electric loads continue to grow, the power system needs additional generation resources to meet these new loads and to replace retiring generation.
Although energy efficiency and distributed energy resources can meet part of these needs, the nation will require new central or large-scale generation — including both renewable and thermal — in the foreseeable future.
Policymakers and regulators are deeply concerned about ensuring adequate resources to meet the system’s future reliability needs, which raises the question of how to attract economic new generation resources, and retaining existing resources. The current federal structure and the decentralized, multilateral scheduling approach for generation resources potentially carry inefficiencies in dispatch and in capacity consolidation.
At the same time, competitive electric wholesale markets are evolving in the country. A competitive market allows for the entry of “merchant” generation that relies solely on market-based revenue streams, without the need for long-term contractual support from distribution utilities (DISCOMs). Developing a competitive wholesale market paradigm where merchants can thrive, however, will take a significant amount of time. Meanwhile, there will continue to be a need for some kind of long-term contracts between DISCOMs and independent power producers (IPPs) to provide assurance that generators can recover their investment costs.1
The question then is how these contracts should be structured. Should they be modeled after many current power purchase agreements (PPAs) that are “physical” in nature, as discussed in the next section, or should the sector move to a financially settled contract (FSC) structure that serves the same purpose but could be more efficient?
In this blog,2 we describe the features of a physical PPA versus an FSC and the criteria for evaluating them, before articulating the benefits of moving to FSC contracts from traditional physical PPAs.
The recent development of a virtual PPA route for large private consumers, and the growing discussion around accommodating financial instruments such as contracts for differences (CfDs) more broadly in regulation, point to the growing recognition of the potential of FSCs as a primary tool for striking future long-term contracts.3 As discussed in later sections, FSC contracts not only support project finance, but they also provide incentives consistent with market price signals, thus increasing efficiency in the system.
In future blogs we will address specific use cases with examples of FSCs with both renewable and thermal resources and explain how to potentially transition the current physical PPA contracts into FSCs.
Physical Power Purchase Agreements Versus Financially Settled Contracts
In a physical PPA, the buyer generally commits to purchasing physical electricity. As the buyer thus owns the electricity, this is called a “physical” trade. By contrast, a financially settled contract does not involve the physical delivery of power. The buyer, therefore, does not “own” the electricity, but rather the financial flows in the FSC enable the buyer to purchase energy from the market, effectively at the price determined in the FSC. The generator will sell into the market; they will have stronger incentives shaping their operation of the power plant under an FSC, based on market price signals.
In a physical PPA, the buyer commits to purchasing physical electricity and thus owns the electricity. This is called a “physical” trade. A financially settled contract, in contrast, does not involve the physical delivery of power, and the buyer does not “own” the electricity.
Physical PPAs tend to be long-term in nature, such as 10-20 years, whereas FSCs can range from short– to medium– to long–term. Both can be bilaterally negotiated between the buyer and seller, but (some) FSCs can also be traded in organized financial markets.
They can both be structured to provide certainty in revenue to the IPP and to provide a hedge to the buyer. However, each structure has different implications regarding the incentive signals for commitment and dispatch of the power plants, as well as the alignment of generator operations with market price signals, which thus affects the overall efficiency of the system.
Presently the dominant type of contracts in India are physical PPAs, with 87% of energy contracted through PPAs of medium– to long–term structure.4
Financially Settled Contract Instruments
The financial instruments used in power contracts could include call options, contracts for difference, futures, forwards, swaps and similar mechanisms.5
With a call option, the buyer pays a “call premium” to the seller for the right to a payment of the excess of the market clearing price over contracted strike price for the capacity contracted. With a CfD, the buyer and seller agree to a contract strike price. If the market clearing price is higher than the strike price, the seller pays the difference between the market price and strike price to the buyer and vice versa if the market clearing price is lower. In (financial) forward markets, commitments are made by buyers and sellers for financial flows that allow parties to lock in a price for the purchase and sale of a given quantity of energy in the future. Futures markets are like forward markets but offer more standardized products by organized market makers. Swaps involve two parties that exchange cash flows from different financial instruments or assets over a specified period.6
With all these instruments, there is no physical exchange of electricity between buyers and sellers, and financial flows are independent of the physical behaviors of resources, such as whether they are offered to the market.7 However, the buyers and sellers could agree on additional contractual terms if they so choose. This might include for example, a requirement for FSCs to be linked to a physical electricity generation asset, existing or new build, as is standard with renewable CfDs in Britain and call options for dispatchable plant in Italy.
Example Use Case for Financially Settled Contracts
In a simplified example that could apply to a thermal plant, assume a two-sided CfD is struck for a given volume of capacity between a buyer (DISCOM) and a seller (IPP), with a strike price ideally discovered in competitive auction that is above the IPP’s variable cost. Assume a design where financial flows are independent of the actual physical scheduling of the contracted resource — rather, financial flows link only to the difference between the strike price and market clearing price. In the figure below, we present three scenarios, where:
- The market price is higher (MP high) than the strike price (SP).
- The market price (MP mid) is lower than the strike price but above variable cost (VC).
- The market price (MP low) dips below variable cost.
Illustration of a two-sided CfD
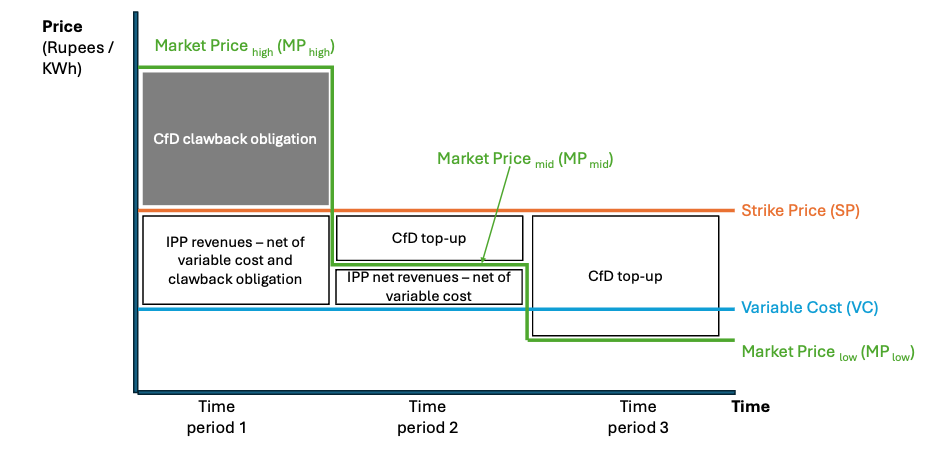
Note: In all scenarios, the DISCOM effectively buys the contracted volume of energy at the strike price, and the power plant receives rents of at least the difference between strike price and variable cost.
The implications for both the buyer and seller are as follows.
- When the market price is higher than the strike price, the IPP will have an incentive to offer and sell its output in the market. This is because — regardless of whether it offers the resource to the market — it has a “clawback” obligation under the CfD to return to the buyer the difference between the market price and strike price (MP high – SP) for each unit of capacity contracted in the CfD. Selling on the market at a price higher than the strike price means it enjoys net revenues of the high market price minus variable cost (MP high – VC), which can finance the cash outflows for the difference between the high market price and the strike price (MP high – SP). Thus, the IPP retains as a margin from the difference between the strike price and variable cost that will help cover its fixed costs.
The buyer, on the other hand, has a cash outflow for purchasing power from the market at a price that exceeds the strike price, and receives a cash inflow of the market price minus strike price (MP high – SP) from the IPP, for a net price of the strike price. Thus, the buyer and seller have effectively hedged and the IPP has the correct incentive to operate according to the market signals. - When the market price is lower than the strike price but higher than the variable cost, the IPP receives from the buyer a “top-up” payment of strike price minus market price (SP – MP mid), irrespective of whether it offers the capacity to the market. This leaves intact the incentive for the IPP to offer and sell its output in the market. The IPP’s resulting net cash inflow from the market will be market price minus variable cost (MP mid – VC) and from the buyer strike price minus market price (SP- MP mid).
The IPP essentially retains as a margin the difference between the strike price and the variable cost that will help cover its fixed costs. The buyer, on the other hand, has a cash outflow for purchasing power from the market at this market price and pays to the IPP an amount of strike price minus market price (SP- MP mid), for a net price of the strike price. Thus, the buyer and seller have effectively hedged and the IPP has the correct incentive to operate as the market price dictates. - When the market price is below the IPP’s variable cost, the IPP receives from the buyer a top-up payment of the strike price minus market price (SP – MP low), irrespective of whether it offers its output to the market. For the IPP, the value of offering and selling its output in the market is negative, as the variable cost exceeds the market price. So, the resource is, correctly, not scheduled in the market. Thus, the IPP’s net cash inflow from the market is zero, and the buyer provides the IPP with a margin of strike price minus market price (SP- MP low) that will help cover its fixed costs. In this transaction, the buyer has a cash outflow for purchasing power from the market at the strike price.
In sum, the buyer has effectively hedged, the IPP has correct incentives to operate accordingly — in this case, by not scheduling in the market — and the IPP has a margin to contribute toward fixed cost recovery. The bumper margins for the IPP in time period 3 may, to some extent, be captured by consumers through competition in setting the strike price.
Although the CfD exposes the generator to fuel price volatility, the generator can hedge variable cost volatility separately in contracts with fuel suppliers. (In our next article, we show how call options can hedge this fuel input price volatility within the FSC through strike price indexation.)
Overall, this example illustrates how a CfD helps provide revenue certainty for the IPP if it operates in alignment with market prices.8 It shows how the CfD provides signals for resources to ensure they are available to schedule when prices are high, and to refrain from scheduling when they are so low that the resource is not in merit. It also shows how CfDs can limit the buyer’s exposure to high prices. Instruments like FSCs send efficient signals to flexible resources that accommodate the variability of renewables. This benefit will only grow in value as renewable penetrations in India increase and prices become more volatile. FSCs, therefore, help future-proof the system.
Criteria For Evaluating Physical Versus Financial Contracts
Criteria for evaluating which type of contract is preferred include:
- Alignment of the generator’s operation incentives with market price signals.
- IPPs should operate when it is economic to do so, supporting efficient scheduling.
- Availability during system scarcity, guided by market price signals.
- Remove or minimize the IPP’s incentive to exercise market power.
- The certainty, stability and predictability of revenue streams to the IPP, to enable it to finance the investment.
- Regulatory certainty for buyers and sellers.
- Fair pricing for both buyer and seller.
- The contribution to resource adequacy to maintain system reliability.
Benefits Of Financially Settled Contracts Over Traditional Physical Power Purchase Agreements
Both traditional PPAs and FSCs provide revenue certainty to the sellers, the IPPs. They also provide price certainty to buyers. Both support resource adequacy under the right underlying regulatory framework, such as a requirement that FSCs be tied to a physical resource, and in the structure of resource adequacy penalty and settlement arrangements.9
In certain physical PPAs, the terms and conditions of the contract are such that some of the generators are not scheduled even if their marginal running or variable cost is less than the market price, and sometimes they are scheduled even if their marginal cost is higher than the market price. This happens at times because generation scheduling currently follows a decentralized merit order, where each DISCOM may optimize only within its own portfolio. This reduces the efficiency of the system and costs consumers money.
FSCs overcome this problem by motivating resources to participate in markets, where they are scheduled according to the overall merit order instead of within individual silos of each DISCOM’s contracted resources. These contracts drive efficient scheduling behaviors when there is system scarcity. Thus, FSCs provide better incentives for the generator to operate in alignment with market price signals.
In sum, the FSC allows for
- Greater market liquidity, assists price discovery, reveals important information about the value of different resources and informs investment choices.
- Surplus capacity of any DISCOM to be identified in the market and scheduled by other DISCOMs, ensuring resources are not operated in silos. This supports efficient scheduling.
- IPPs to have an incentive signal to offer their output into the market at their marginal cost and to self-curtail when market prices fall below their variable costs.
- Signals to IPPs when to take a plant off for maintenance, i.e., when market prices are lowest or even negative.
- More visibility of market schedules, which assists the system operator when forming plans to accommodate the expected energy mix (for instance, ensuring sufficient inertia).
- Minimizing the potential for generators to exert undue influence in the market. Market prices above the strike price will not benefit the IPP’s contracted capacity under the CfD.10
Conclusion
As DISCOMs seek new long-term power purchase agreements with independent power producers, we recommend they strongly consider the use of financially settled contracts rather than traditional physical power purchase agreements. Policymakers can help capture the benefits of financially settled contracts by fostering their implementation in regulatory arrangements. The financially settled contract, as demonstrated above, will improve efficiency in the system and lead to lower generation costs and prices for consumers, while retaining revenue certainty for independent power producers and embedding a price hedge for buyers. In future briefings we describe specific use cases for structuring financially settled contracts for renewable and thermal resources and discuss how to transition the current contracts to financially settled contracts where feasible.
- It is assumed here that DISCOMs will not build new generation under traditional cost-of-service regulation but will use competitive bidding practices to procure new resources. ↩︎
- The authors would like to express their appreciation to Mr. Sushil Soonee, who provided helpful insights into earlier drafts of this piece. We would also like to thank experts and thought leaders on Indian electricity arrangements. Finally, thanks to Deborah Bynum for editorial support. ↩︎
- See, for example, Central Electricity Regulatory Commission New Delhi. (n.d.). Draft Guidelines for Virtual Power Purchase Agreements. https://www.cercind.gov.in/2025/draft_reg/Draft%20Guidelines%20for%20VPPAs.pdf ↩︎
- Central Electricity Regulatory Commission. (n.d.). Report on Short-term Power Market in India: 2023-24. https://www.cercind.gov.in/annual-report-23-2024.html ↩︎
- We will not discuss the concept of “tolling arrangements’’ in this blog but will address it in future articles. ↩︎
- The reader can refer to any basic finance textbook for further elaboration on these financial instruments. See also Scott, D., & Morawiecka, M. (2024). The search for two-sided CfD design efficiency — a Shakespearean history. https://blueprint.raponline.org/deep-dive/cfd-part-ii ↩︎
- A notable exception is renewables CfD designs which couple financial payment with physical performance, as used in Britain, for example. ↩︎
- Note that this is a simplified example. Future briefings will elaborate on single versus multi-part (tariff) contract arrangements. ↩︎
- Potential “free-rider” problems — where under-contracted DISCOMs rely on energy provided by capacity contracted through FSCs by other DISCOMs, without contributing to the cost of that capacity — could be overcome by embedding significant penalties for shortfalls, either directly in wholesale price formation or through the resource adequacy penalty framework. ↩︎
- Future blogs will discuss regulatory oversight requirements to ensure that the FSCs are structured to prevent unscrupulous behavior by market participants and to protect both buyers and sellers. ↩︎
A version of this article originally appeared in Power Line.
Photo: Santhosh Varghese via Shutterstock.